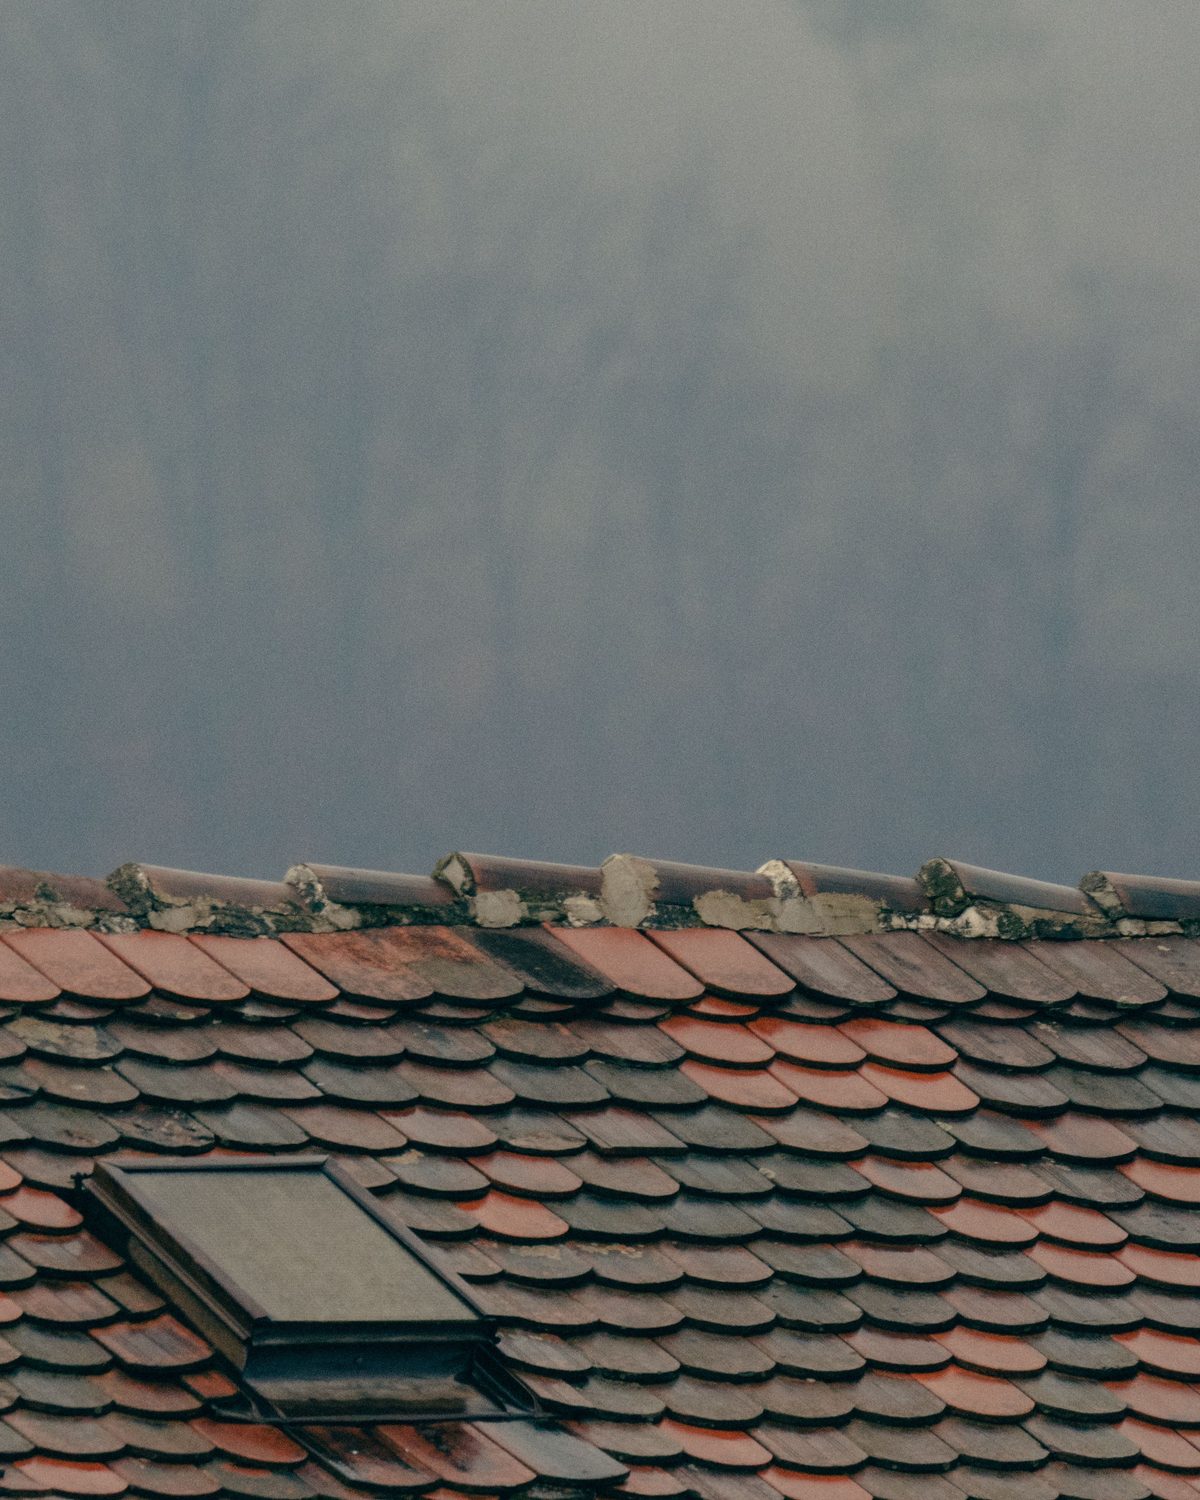
Hail damages a roof by knocking granules loose and fracturing the mat underneath, and most of that damage is invisible from the driveway. A hail claim therefore turns on evidence: what was struck, when it was struck, and whether the pattern on the roof matches a storm on the record.
That is the whole argument you are making. Insurers do not pay for a roof that has simply grown old. Subject to your policy, they pay for damage caused by a covered event on a date you can name. Every step below exists to connect those two things and to put the connection in writing before anyone climbs a ladder.
Signs of hail damage
| Roof type | What to look for |
|---|---|
| Asphalt shingles | Dark spots where granules are knocked off, bruises that feel soft, cracked shingles |
| Tile | Cracked, chipped or broken tiles |
| Metal | Dents in panels, flashing and vents |
| Flat roofs | Punctures, fractures in the membrane, damaged surfacing |
A hail bruise on asphalt is a fracture in the mat under the surface, which is why it is felt as much as seen. Granule loss around the impact exposes the asphalt to sun, and that is the mechanism that shortens the life of the roof. Cracking and splitting that runs with the grain of the shingle is usually age. Round impacts scattered without pattern are usually hail.
Look at everything except the roof
Soft metal around the house records the storm better than the shingles do, and you can photograph all of it from the ground without any risk.
- Gutters, downspouts and the drip edge
- Vents, ridge caps, chimney caps and satellite dishes
- Window screens, shutters, siding and garage doors
- Air conditioning fins and grill lids
- Fences, mailboxes and painted deck rails
Dents in those places are hard to explain as wear. They also show the direction the storm came from, which helps explain why one slope is damaged and another is untouched.
Documenting hail damage
- Photograph hail on the ground with a coin or a ruler for scale, while it is still there
- Note the date and the time the storm passed over
- Save a local weather report, a storm alert or a warning notice for that date
- Photograph every dented surface at ground level, close up and then from further back
- Photograph interior stains, along with the date you first saw them
- Get a professional inspection, because walking a hail struck roof is risky
Take the wide shot as well as the close one. A close photograph of a dent proves a dent. It does not prove the dent is on your house.
Keep the file in one place, named by date, and back it up. A hail claim can run for months, pass between two or three adjusters and end up being argued from photographs alone, so the value of the record grows the longer the claim lasts. Add every letter, estimate and call note to it as you go.
What adjusters look for
Adjusters look for a pattern of impacts consistent with hail, and they separate that pattern from wear, blistering, manufacturing defects and foot traffic. Expect the inspection to include marked off test areas on several slopes, so that damage can be counted in a consistent way rather than described loosely, and expect the adjuster to check the soft metal you photographed for the same reason you photographed it.
Useful questions to ask on the day:
- Which slopes did you walk, and which did you view from the ladder?
- What did you photograph, and will those photographs go in the file?
- Did the soft metal show impacts, and are they recorded?
- What estimating software and price list will the estimate use?
- When will I receive the estimate in writing?
Write the answers down with the date and the adjuster’s name. If something is missing later, a specific question about a specific slope carries far more weight than a general complaint.
Cosmetic versus functional damage
Some policies limit or exclude payment for cosmetic hail damage, meaning dents that change how the roof looks without changing how it works. This wording appears most often on metal roofing and is sometimes added by endorsement at renewal, so check your declarations page and the endorsement list rather than assuming last year’s terms still apply.
The distinction matters because it moves the argument. On a cosmetic limitation, the question is no longer whether hail struck the roof. It is whether the impacts affect performance: a fractured mat, a broken seal, a punctured membrane, a cracked tile that now admits water. An inspection report that addresses function directly is the one that answers this point.
Hail damage and the age of the roof
Age does not disqualify a hail claim, but it changes what the claim is worth. Two things drive that. The first is how your policy values a roof: some settle at replacement cost and release the held back depreciation once the work is finished, and others settle at actual cash value and never release more. The second is an endorsement, common on older roofs in hail exposed markets, that puts the roof surface on its own schedule so that payment falls as the roof ages.
Neither term is visible from the roof. Both are on your declarations page and in the endorsement list attached to it. Read them before you file, because they decide whether a covered hail loss produces a new roof or a contribution towards one, and whether a small claim is worth reporting at all.
Why hail claims get refused
| Reason given | What it means | What answers it |
|---|---|---|
| Wear and tear | The surface failed with age, not with a storm | An inspection describing impacts and distinguishing them from aging |
| No date of loss | The storm claimed for does not match the record | A weather record for the date, plus dated photographs |
| Cosmetic only | The dents do not affect performance | Documentation of fractured mats, broken seals or punctures |
| Mechanical damage | The marks came from tools or foot traffic | Photographs of soft metal impacts elsewhere on the property |
| Prior claim paid | The damage was covered by an earlier settlement | Records of what was repaired and when, with invoices |
The pattern across all five is the same. A refusal is answered with documentation rather than disagreement, and the strongest document is a dated report from someone who went up and described what they found.
When the damage shows up later
Hail rarely causes a leak on the day. Granule loss and mat fractures work slowly, and the first sign inside the house can arrive seasons after the storm that caused it. That is why the date of loss on a hail claim is so often disputed, and why the documentation above is worth gathering as soon as a storm passes even if nothing appears to be wrong.
If water is already coming in, the cause question becomes central and the route runs through our roof leak guide. If the same storm brought wind, missing shingles and lifted edges are scoped differently from impacts, so read the storm and wind guide alongside this one and make sure both appear in the claim.
Next steps
Get the ground level photographs and the weather record today, then get an inspection that names the damage, states the cause and dates it. When you have that, follow the full claim process from filing through to the adjuster visit and the estimate review.
This page is general information, not legal, financial or insurance advice. What we do is inspect the roof and write the damage down. Where a claim needs somebody to act for you, we can introduce you to a partner who is a licensed public adjuster or an attorney in your state. Your policy and your carrier decide what is covered.
In this section
- Hail and your policyThe policy wording that decides a hail roof claim: cosmetic exclusions, roof payment schedules, separate hail deductibles and what changes at renewal.
- Hail claim basicsHow a hail damage insurance claim works from the storm to the final payment: notice, deadlines, the adjuster visit, the scope, supplements and the two payments.
- Hail payoutWhy there is no average hail roof payout, how a hail settlement is calculated, and which four figures decide what actually reaches you.
Common questions
How long after a hail storm can I file a roof claim?
There is no single answer. Your policy sets the notice requirement, usually worded as prompt notice or notice as soon as reasonably possible, and your state may set its own outside limits.
- Report the damage as soon as you find it
- Read the conditions section of your policy for the wording that binds you
- Delay lets fresh bruises weather until they look like ordinary aging
- The storm record gets harder to tie to your address over several seasons
Insurers ask which storm caused this, and an answer of roughly two years ago invites a wear and tear decision. If you are already late, file anyway and record why it was not found sooner, with the date of discovery. Ask the insurer to confirm in writing which deadlines apply, and ask your state insurance department what it requires.
What size hail damages a roof?
No single size decides it. Impact energy depends on the stone size, its density, the wind driving it and the angle it strikes, and resistance depends on the material, its age and the temperature.
- Small stones can damage a tired roof that would have shrugged them off
- So an adjuster reads the roof rather than the forecast
- A hail report for your area neither proves nor disproves your claim
- Asphalt loses flexibility and the mat fractures, tile chips, metal dents
A report of large stones a mile away does not establish what fell over your house, and metal denting without losing function is where cosmetic limitations come in. What helps is an inspection describing the impacts themselves: where they are, how they are distributed, what they did to the surface and how they differ from wear or foot traffic.
Will insurance replace the whole roof or only the damaged slopes?
It depends on your policy, on what the adjuster records and on your state's rules. Insurers scope roofs slope by slope, so a roof with impacts on one elevation can come back approved for that elevation alone.
- Whether the rest follows turns on matching and on a sound repair
- If your shingle is discontinued and nothing blends, that argues for more
- Document it with written confirmation from a supplier, not an assertion
- States treat matching of undamaged material differently, and some are silent
See the [state pages](/states/) for how to find your own answer. If the scope comes back narrower than your roofer expected, ask for the adjuster's report and photographs, ask which slopes were walked, and put the disagreement in writing with the evidence attached. Missed items are normally handled as a supplement rather than a fresh claim.
Does filing a hail claim raise my premium?
It can, and the honest answer is that it depends on your carrier, your state and how the claim is coded. Insurers keep a record of every claim you report, including ones they decline to pay.
- Other carriers see that history when you shop
- Ask your agent what it does at renewal before filing near your deductible
- Some carriers treat weather losses differently from fault losses
- Some states restrict what an insurer may do after a catastrophe claim
- Neither is universal, so get your own answer in writing
On roofs the larger factor at renewal is often the roof itself, since age, material and condition drive underwriting. A report showing a sound maintained roof is useful whatever happens to the claim. None of this is a reason to leave real damage unreported, because unrepaired storm damage becomes the reason a later claim is denied.
Can an adjuster deny hail damage my roofer found?
Yes. The adjuster decides what goes into the insurer's scope, and two people can walk the same roof and write it differently. That is not the end of the claim.
- What moves a file is evidence the adjuster did not have
- Ask for the report, the photographs and which slopes were walked
- Files are often decided on partial inspections
- Send an independent inspection with photographs and the weather record
- Ask for your roofer to be present at the reinspection
If the disagreement is about amount rather than whether damage exists, read your policy for an appraisal clause and check what it binds. Your state insurance department takes complaints at no cost. Our part is the inspection and the document. If you would rather somebody acted for you, ask and we will introduce you to a partner who is a licensed public adjuster or an attorney in your state.